An automatic monetary thermostat for the future digital CFA franc, grounded in long-run cointegration and dynamic optimisation.
π White Paper (PDF) π Interactive Dashboard Request a demoThe CFA franc faces four simultaneous pressures that threaten the stability of the CEMAC zone and the effectiveness of its monetary policy.
USDT and USDC capture digital savings across Africa. They drain foreign reserves, escape BEAC control, and accelerate the silent dollarisation of the economy.
Under a fixed peg, CEMAC inflation is determined in the long run by euro-area inflation. Our empirical work confirms a pass-through coefficient close to 1.
The 50% devaluation of the CFA franc triggered a durable inflationary shock. A frozen model would have been blind for years: quarterly re-estimation is indispensable.
Cameroon's accession to PAPSS introduces new cross-border flows that alter domestic money demand. The thermostat must monitor them in real time.
Instead of leaving monetary policy to discretion, we anchor it in a transparent, mathematically optimal, and externally verifiable rule.
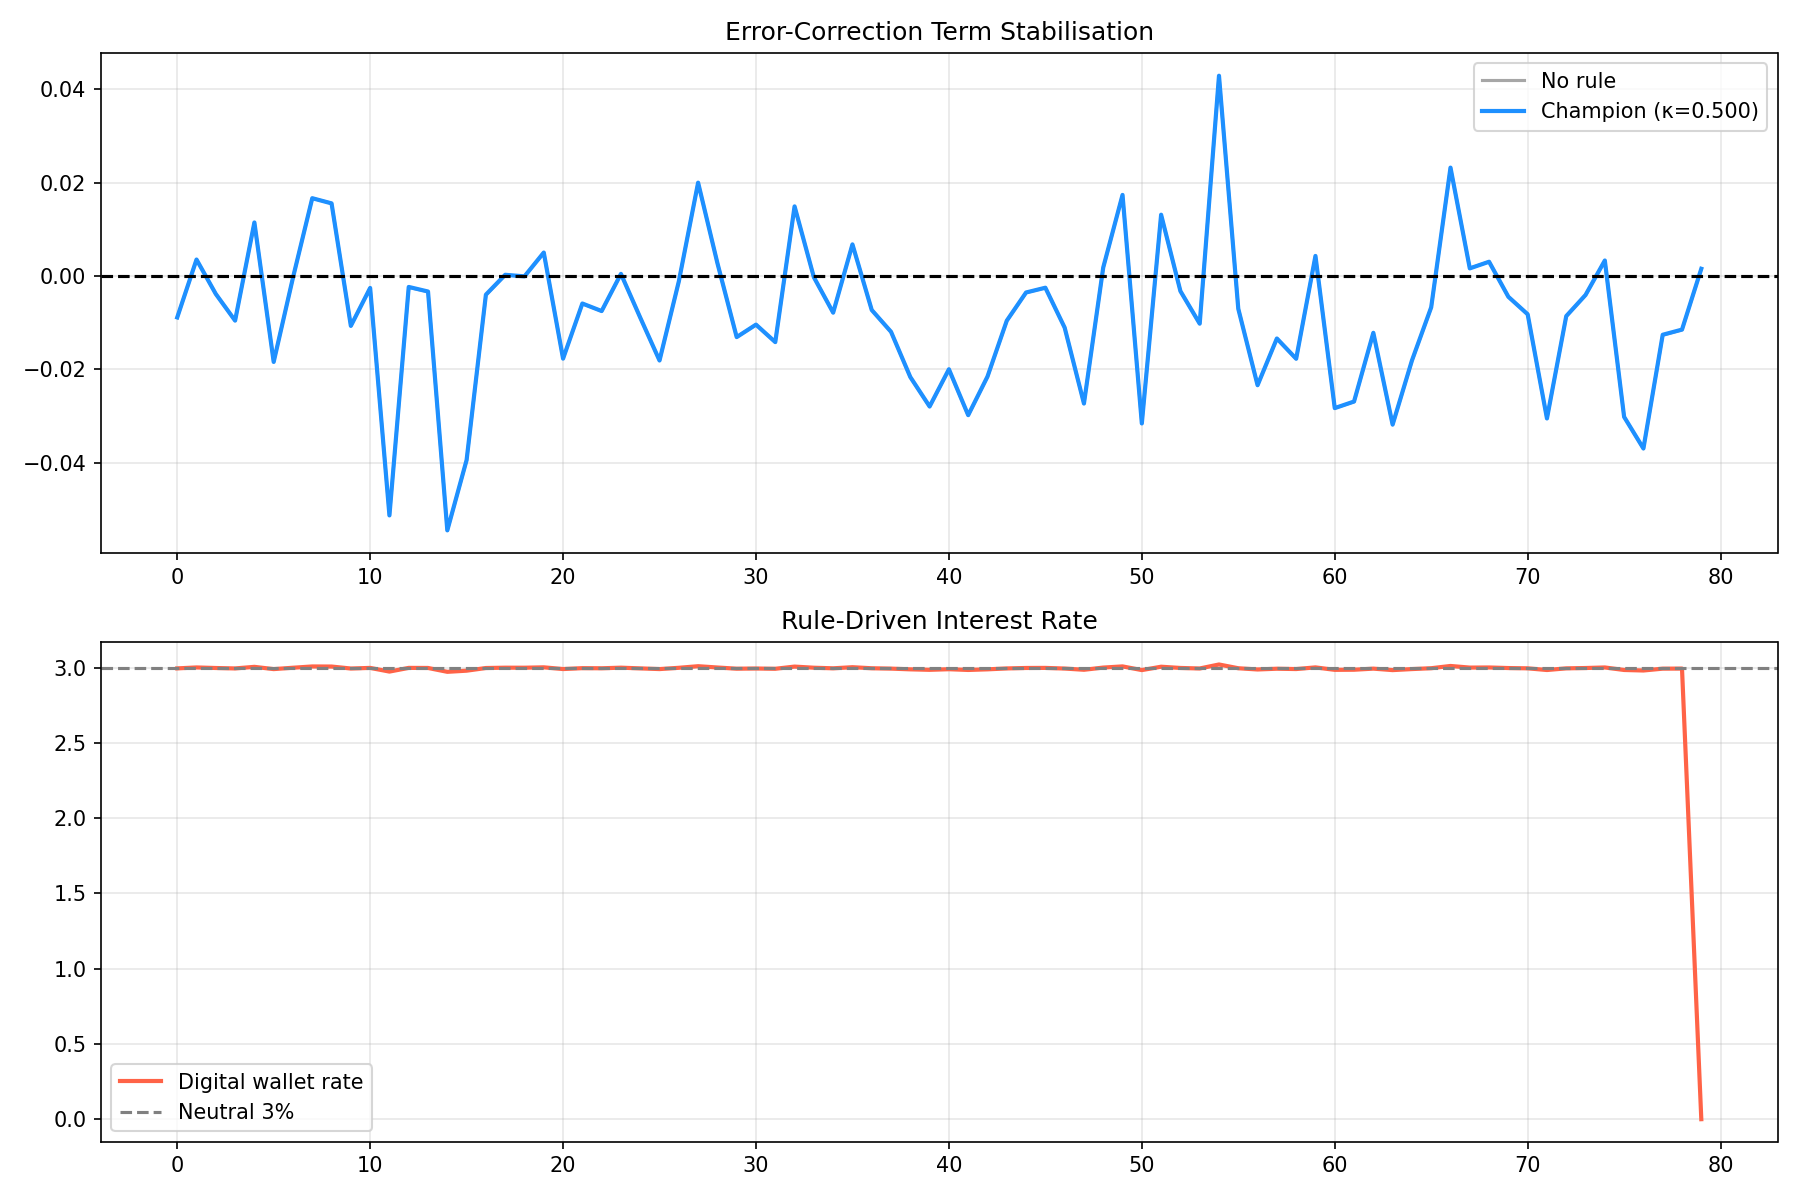
The digital rate rule
where ECT = deviation of money supply from its long-run equilibrium
Long-run money demand (M2, GDP, inflation) is cointegrated across all six CEMAC countries. Deviations correct themselves naturally β we automate that correction.
kappa is not an arbitrary number. It is the solution of the Bellman equation for a central bank minimising ECT variance and rate volatility. Result: kappa ~ 0.46.
Every rate decision is signed (ECDSA), timestamped, and hash-chained. The IMF or the French Treasury can verify the full history using only the engine's public key.
Champion/challenger, signed versioning, Prometheus/Grafana monitoring, automatic rollback, chaos engineering. Built for production, not for a paper.
We follow the champion/challenger framework used by the Federal Reserve, the ECB, and the Bank of England.
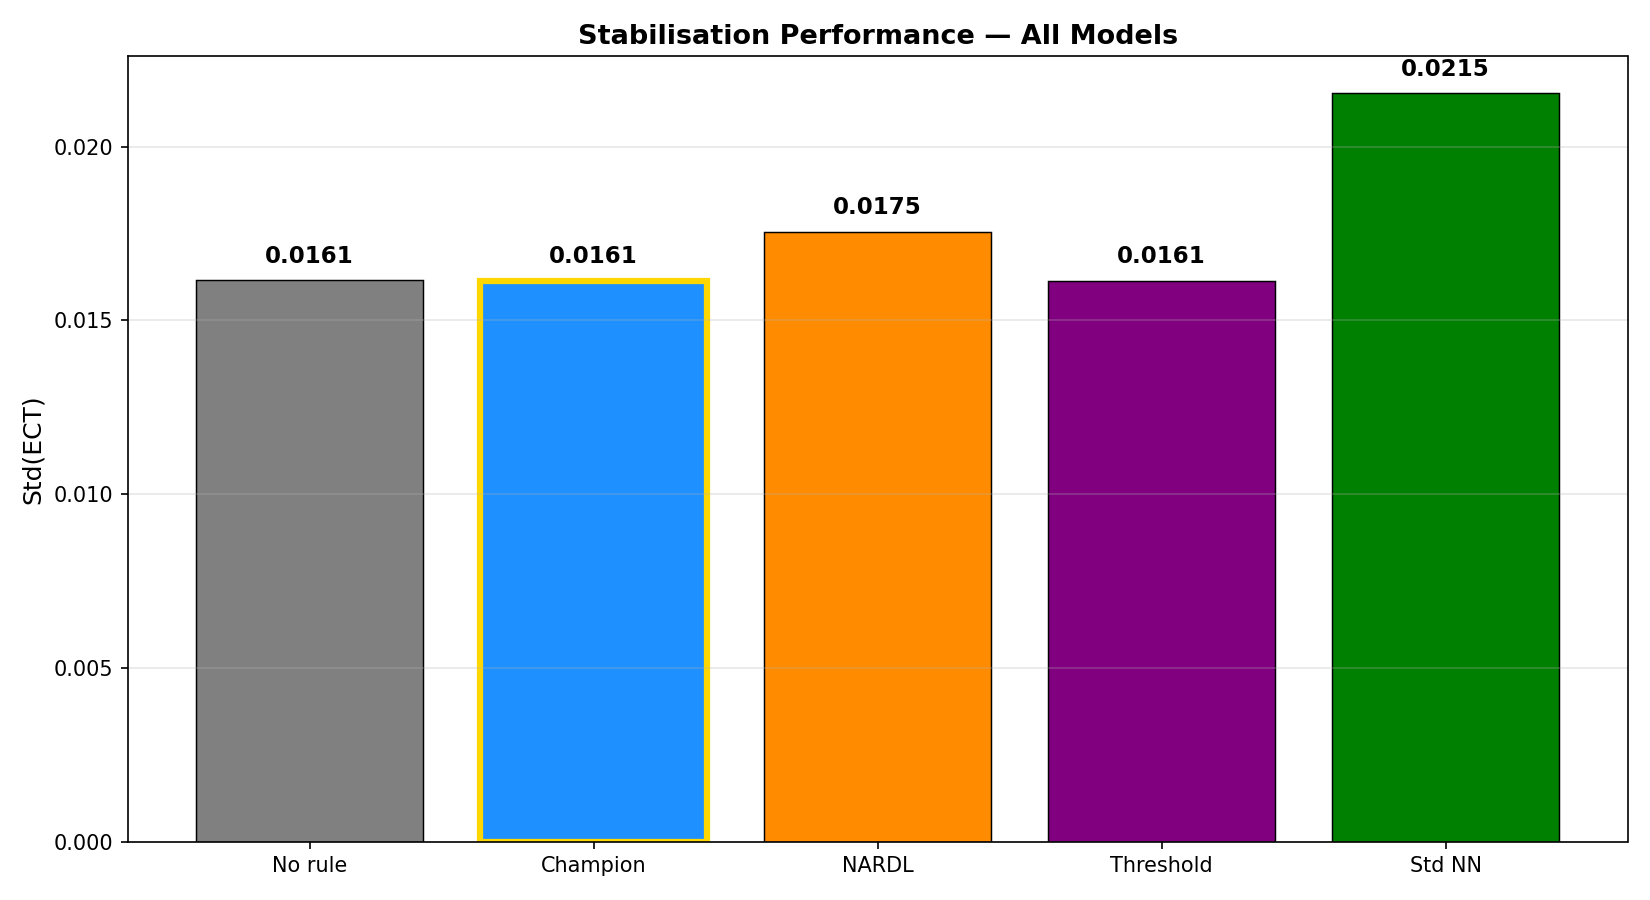
Linear DOLS + LQR β transparent, causally identified, mathematically optimal. This model computes the rate in production.
Asymmetric NARDL (kappa+ for reserve defence, kappaβ for easing) and a crisis mode (higher kappa when |ECT| crosses an MPC-approved threshold).
CEMAC-NN and KAN β run offline to validate the champion. They never modify production without MPC approval.
Bridge equations and dynamic factor models detect shocks within days using high-frequency indicators (oil, mobile money, PAPSS flows).
Founder & Principal Monetary Architect
Statistician-economist, former Senior Statistical Analyst at the National Bank of Canada (risk model validation, sensitive financial data under strict regulatory frameworks), PhD candidate in econometrics. He designed and built the entire "Digital CFA Franc" prototype β from the cointegration pipeline to the containerised rule engine, including the cryptographic audit trail.
Consilium CFA is an independent research centre specialised in monetary stability in the Franc Zone. We design transparent, sovereign, and mathematically optimal monetary policy tools for African central banks.
Complete methodology, architecture, simulations, governance. (17 chapters)
DownloadStatistical tests, API, SND30, glossary, KAN, kappa, nowcasting, causal inference.
DownloadThe 5 service tiers: feasibility, prototype, integration, governance, maintenance.
DownloadInternal directive, rollout plan, competitive analysis, formal letter.
DownloadAll of our research is public, auditable, and reproducible.
Executable proof of concept β full pipeline (DOLS, NARDL, NN, threshold), calibration, backtests, cryptographic signing.
View on GitHubComplete project β documentation, governance, service briefs, presentations, technical annexes.
View on GitHubWe can organise a working session in YaoundΓ© or via videoconference with your technical teams.
Email: aymar.makanda@consilium-cfa.com
Phone / WhatsApp: +1 438 519 2618
Address: YaoundΓ©, Cameroon
Full contact pageFlagship Initiative
A cointegration-based monetary architecture for intra-African trade β PhD research at McGill University.
Visit afroproject.africa β